Then in account 4211 they can see the portion of the cost that was paid by the employees. The company’s income statement will report the combination of the amounts in accounts 4210 and 4211 in order to show the company’s actual expense of $8,000 ($10,000 minus $2,000). Contra expense accounts come in various forms, each serving a unique purpose in financial accounting. When a company returns goods to a supplier due to defects or other issues, the value of these returns is recorded in this account.
Presentation of Contra Accounts
This depreciation is saved in a contra asset account called accumulated depreciation. The accumulated depreciation account has a credit balance and is used to reduce the carrying value of the equipment. The balance sheet would report equipment at its historical cost and then subtract the accumulated depreciation. Examples of contra expenses include specific scenarios where contra expense accounts are https://www.bookstime.com/ used to adjust expense recognition and align it with contra revenue accounts for a more accurate financial picture. The most common contra account is the accumulated depreciation account, which offsets the fixed asset account. Taken together, the asset account and contra asset account reveal the net amount of fixed assets still remaining.
Contra Account
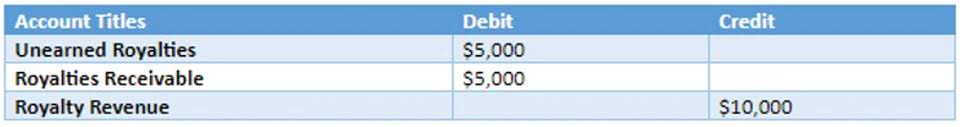
Contra expense accounts are specialized accounts used to record reductions in specific expense categories, providing a clearer view of net expenses. These accounts are typically paired with a corresponding expense account, allowing for a more detailed and accurate representation of financial activities. For instance, if a company receives a rebate on a previously recorded expense, the rebate would be recorded in a contra expense account, effectively reducing the total expense reported. For the purpose of presentation on primary financial statements, we are often concerned only with the net figure of two similar classes/balances which we determine by subtracting one account from the another. For example, it is not very useful to show the PPE cost account and the related accumulated depreciation account separately on the balance sheet.
Why are Contra Accounts Inportant?
For example, Accumulated Depreciation is a contra asset account, because its credit balance is contra to the debit balance for an asset account. Contra Asset Account – A contra asset account is an asset that carries a credit balance and is used to decrease the balance of another asset on the balance. Implementing cost-saving initiatives such as negotiating better terms with suppliers, streamlining processes, and leveraging technology can help reduce contra expenses.
What Are Some Examples of Contra Expenses?
This transparency is crucial for maintaining the trust of investors, creditors, and other stakeholders, as it demonstrates a commitment to accurate and honest financial reporting. Contra accounts exist when the account reported on the balance sheet needs to be reduced by a different account to show its true value. For example, GAAP accounting (or generally accepted accounting principles) requires fixed assets to be reported at cost on the balance sheet, but, over time, that value depreciates as the assets are used.
In the financial statements the purchases account would be offset against the contra expense accounts to show the net purchases. The use of contra expense accounts also aids in identifying trends and anomalies in expense patterns. For instance, a sudden increase in purchase returns recorded in a contra expense account might signal issues with supplier quality or internal procurement processes. Conversely, consistent discounts received could indicate strong supplier relationships and effective negotiation tactics. These insights allow analysts to make more informed recommendations for operational improvements and strategic planning. Expense accounts and the contra expense accounts with which they are paired are typically combined in the income statement in a single line item, so that readers are not aware that a contra account even exists.
Example of a Contra Expense Account
An allowance for doubtful accounts is a contra asset account that petty cash is used to offset Accounts Receivable on the balance sheet. This account is used to estimate the amount of money that is not likely to be collected from customers. Contra expenses are essentially deductions or reductions from regular expenses, recorded separately to highlight their unique nature. They are used to offset and reduce the impact of related expenses, providing a clearer picture of the company’s financial position. In this article, we will delve into the definition of a contra expense, its importance in financial reporting, and how companies can effectively manage their contra expenses. Let’s consider a fictional example of a small retail business called “GadgetHub” to illustrate the use of a contra expense account in financial accounting.
- These three types of contra accounts are used to reduce liabilities, equity, and revenue which all have natural credit balances.
- For example, contra revenue accounts can be used to track the full cost of sales less any discounts or returns.
- Various types of contra expense accounts exist, each designed to offset specific expenses and improve the accuracy of financial statements through precise expense recognition.
- ABC Computers makes sales of 90,000; unfortunately, due to a fault in a product, they received returns of 2,500.
- There are two major methods of determining what should be booked into a contra account.
- The following are examples of contra expense accounts used in double entry bookkeeping.
- For example, an increase in the form of a credit to allowance for doubtful accounts is also recorded as a debit to increase bad debt expense.
Conclusion for Contra in Accounting
As evident from the table below, each contra account has a parent account whose normal balance is often exactly opposite of the normal balance of the relevant contra account. Accounting sources advise that what is contra expense the full amount of a bad debt be written off to the profit and loss account or a provision for bad debts as soon as it is foreseen. Accounts receivable (AR) is the balance of money due to a firm for goods or services delivered or used but not yet paid for by customers. The difference between an asset’s account balance and the contra account balance is known as the book value. In footnote 3, the company reports, “Net property and equipment includes accumulated depreciation and amortization of $25.3 billion as of August 1, 2021 and $24.1 billion as of January 31, 2021.” There are various technical definitions of what constitutes a bad debt, depending on accounting conventions, regulatory treatment and the institution provisioning.