The financing activities section generally shows inflows and outflows to or from investors and lenders. If a company issued stock or bonds during the period in question, the proceeds would show up as an inflow. If the company bought back stock or had bonds mature during the period, the payments would show up as an outflow.
What is on a cash flow statement?
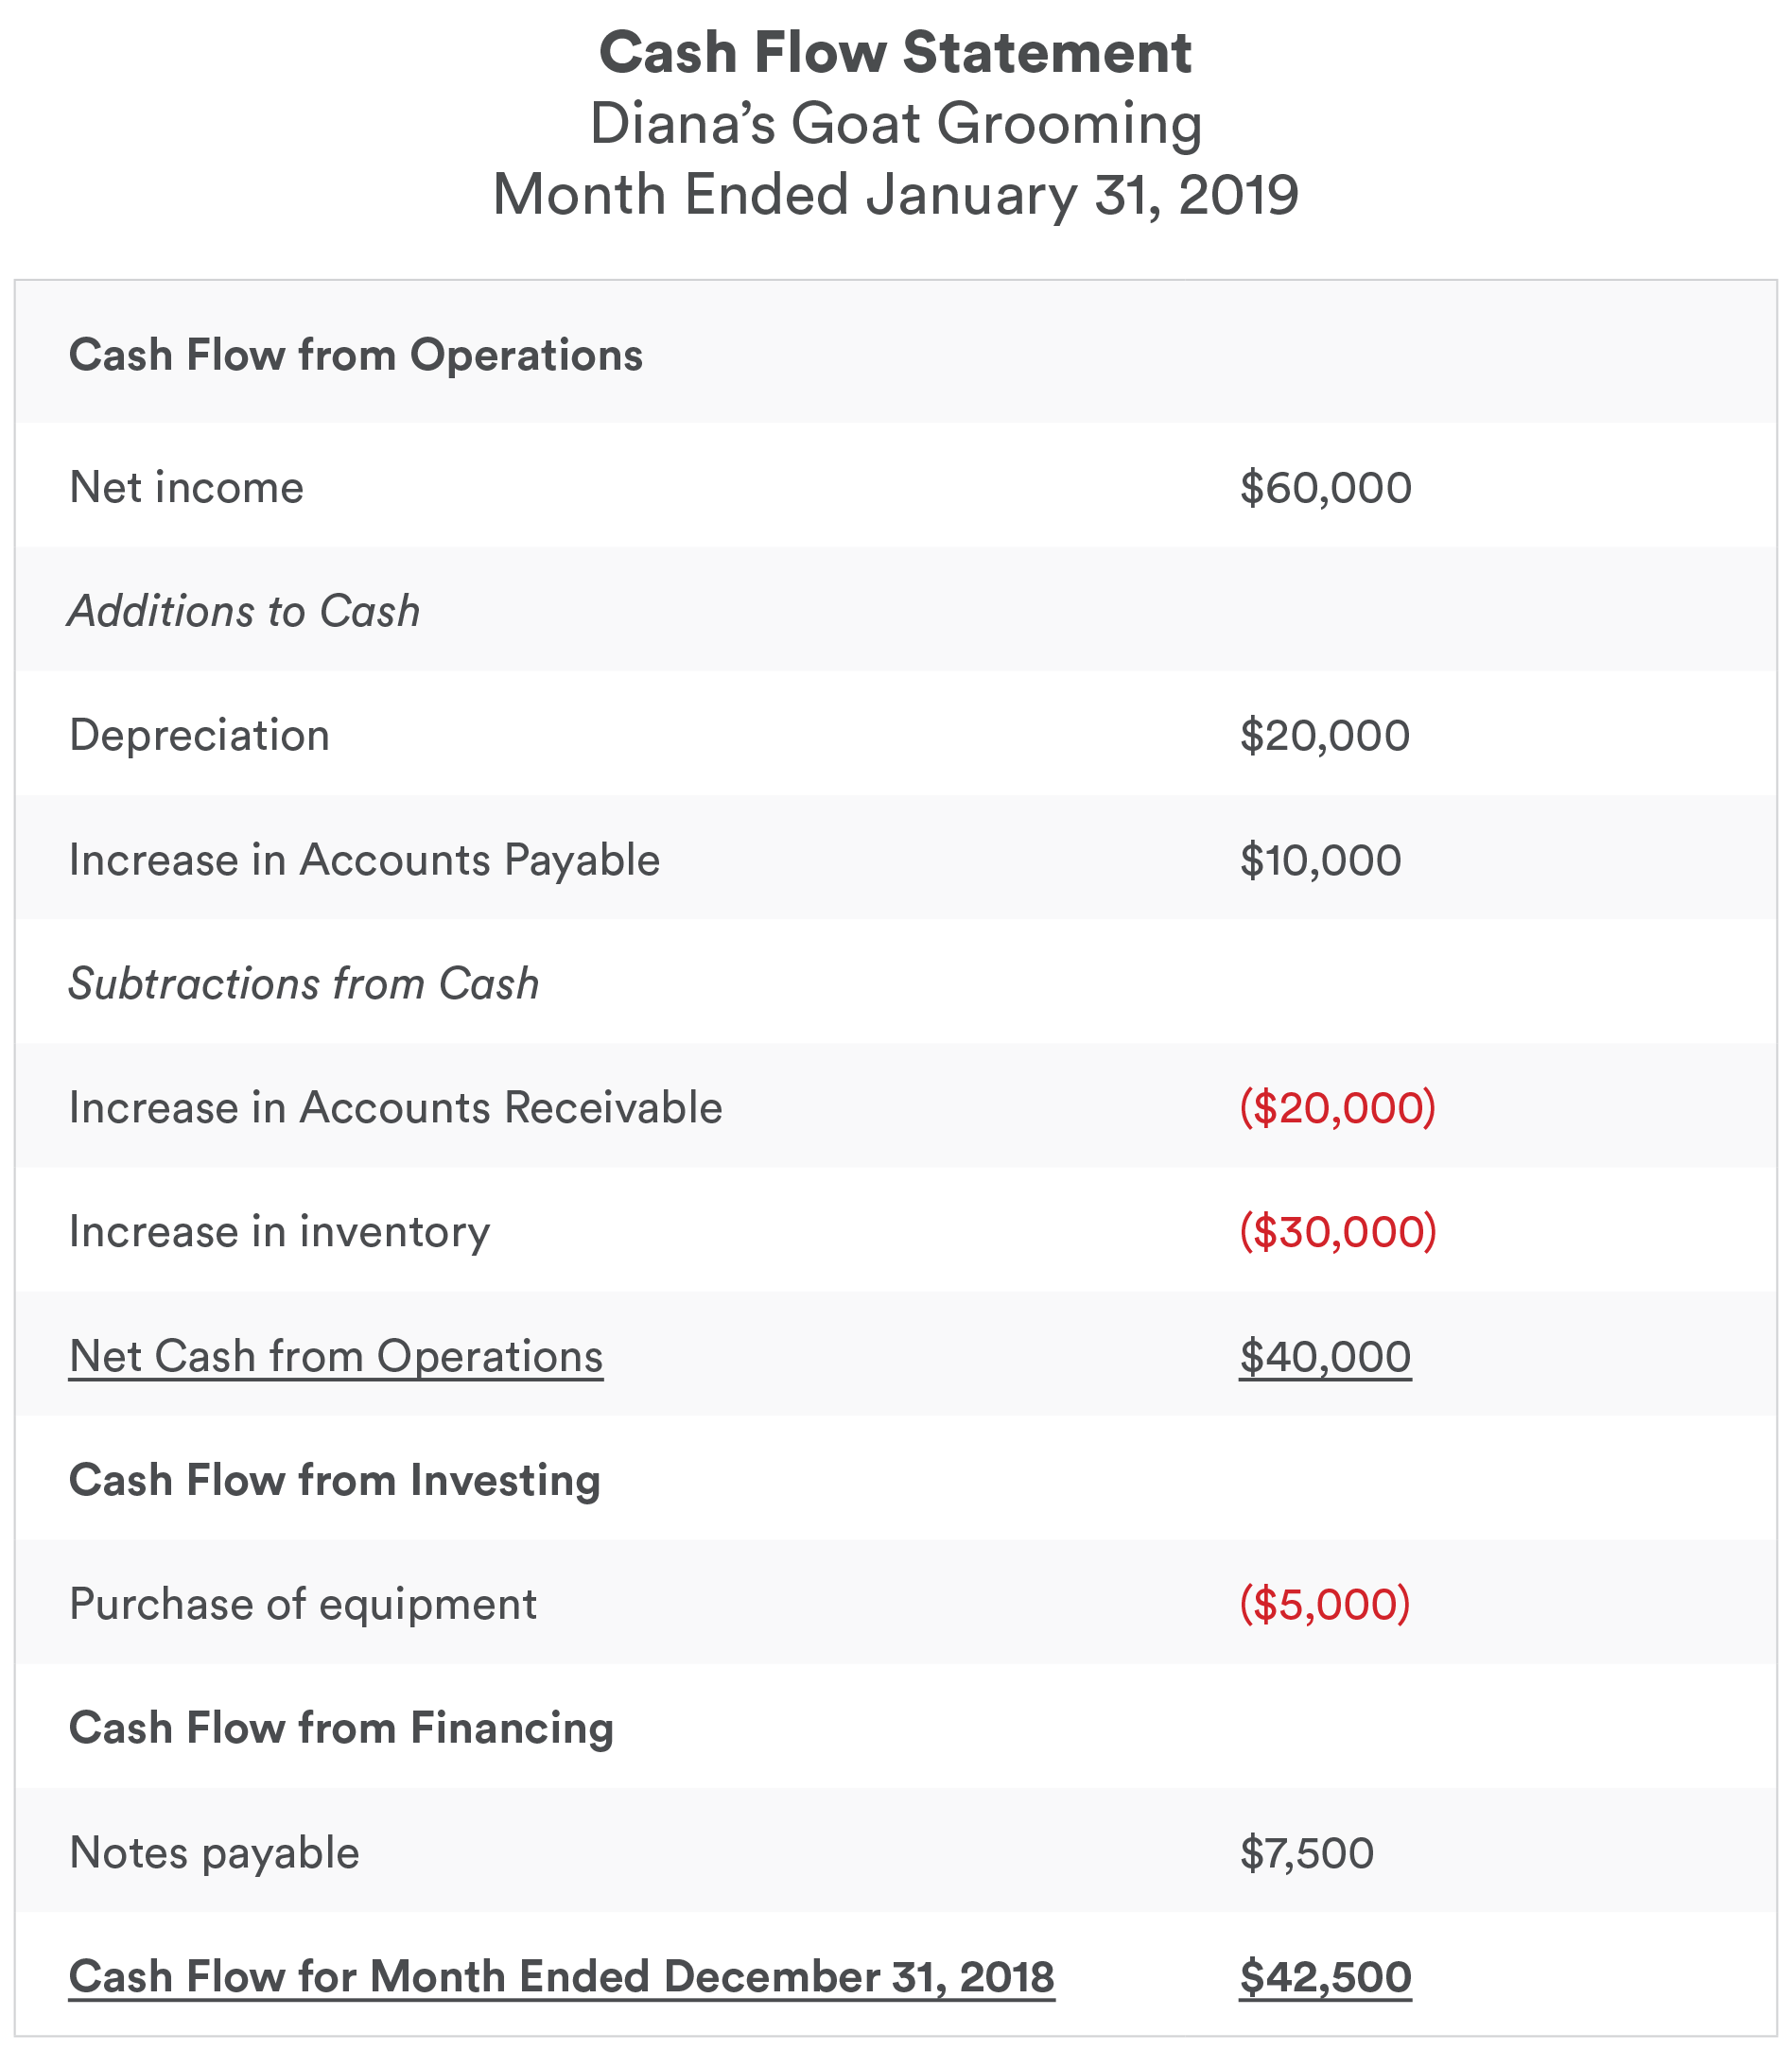
The direct method converts the income statement from the accrual basis to the cash basis. Accountants must consider changes in balance sheet accounts that are related to items on the income statement. The statement of cash flows presents the effects on cash of all significant operating, investing, and financing activities. By reviewing the statement, management can see the effects of its past major policy decisions in quantitative form.
REVIEW PROBLEM 12.4
Common items in this section of the statement include the payment of dividends, issuance of common or preferred stock, and issuance or payment of notes payable (see Figure 5.18). In the above example, the business has net cash of $50,049 from its operating activities and $11,821 from its investing activities. It has a net outflow of cash, which amounts to $7,648 from its financing activities. The first section of the statement of cash flows is described as cash flows from operating activities or shortened to operating activities. Focusing on net income without looking at the real cash inflows and outflows can be misleading, because accrual-basis profits are easier to manipulate than cash-basis profits. In fact, a company with consistent net profits could potentially even go bankrupt.
Everything You Need To Master Financial Modeling
Thus the purchase of long-term investments for $12,000 is shown as a decrease in cash in the investing activities section. Since cash flow statements provide insight into different areas a business used or received cash during a specific period, they’re important financial statements for valuing a company and understanding how it operates. Cash flows from investing activities contains the sum total of the changes that a company experienced during the reporting period in investment gains or losses, as well as from any new investments in or sales of fixed assets. Investing activities include any sources and uses of cash from a company’s investments. Purchases or sales of assets, loans made to vendors or received from customers, or any payments related to mergers and acquisitions (M&A) are included in this category.
Do you own a business?
This cash flow statement shows that Nike started the year with approximately $8.3 million in cash and equivalents. For an investment company or a trading portfolio, equity instruments or receipts for the sale of debt and loans are also included because it is counted as a business activity. If Example Corporation issues additional shares of its common stock, the amount received will be reported as a positive amount. Amounts spent to acquire long-term investments are reported in parentheses, since it required an outflow or use of cash. Next, our company’s long-term debt balance was assumed to be $80m, which is decreased by the mandatory debt amortization of $5m.
- But as you become more familiar with the language of financial statements it may become easier to make sense of them.
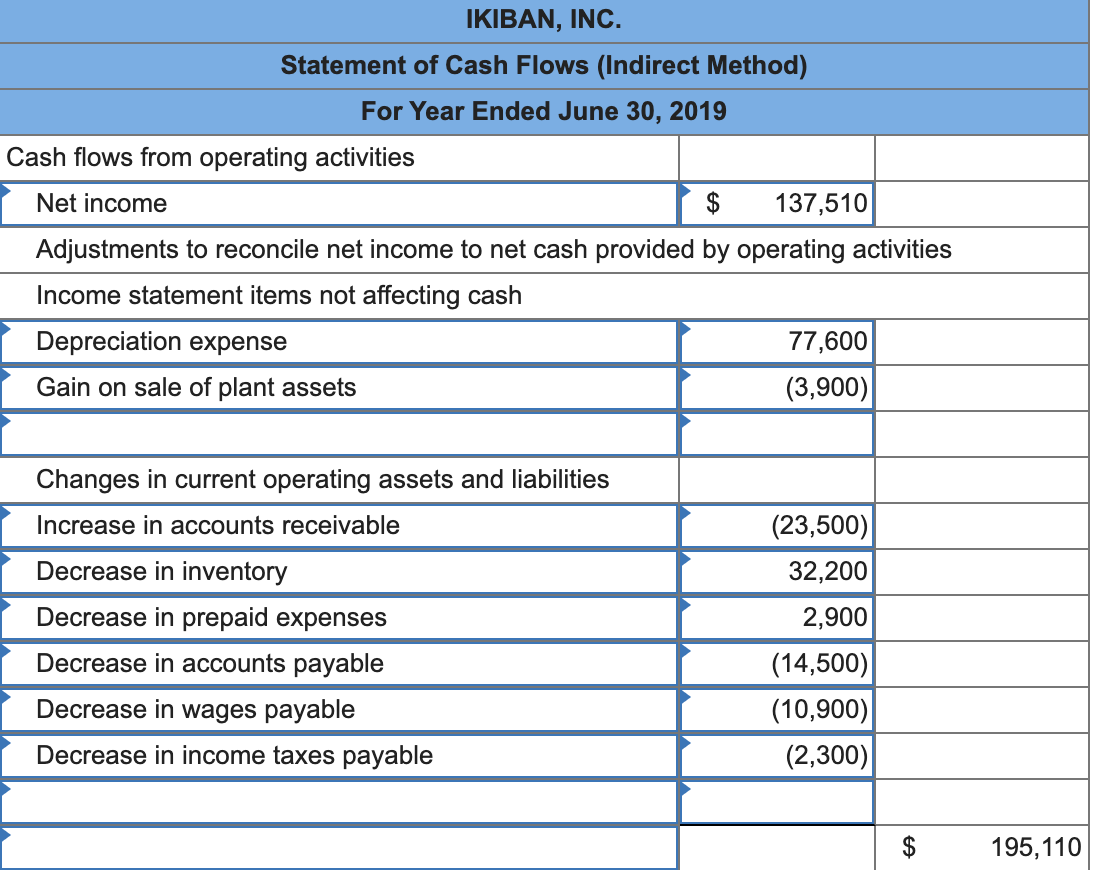
- If the amounts had added up to a negative amount, the description would be “Net cash used by operating activities”.
- It is especially important for deriving a business valuation, since many valuation methods are based on a firm’s net cash flows.
- It is important to note that all positive amounts shown in the statement of cash flows denote an increase in cash, and all negative amounts denote a decrease in cash.
- However, IFRSs permit companies to treat these incomes as either operating or investing activities, depending on their accounting policies and procedures.
This final summary amount indicates that $28,000 more “came in” than was paid out during this year for investing activities. (If it were a net cash outflow, use parenthesis to indicate this.) This is the second of six numbers in the right-hand column. The following section will show you how to prepare the statement of cash flows (indirect method for operating activities section) on page 259 from the financial statements on page 255.
If the amounts had added up to a negative amount, the description would be “Net cash used by operating activities”. The common stock and additional paid-in capital (APIC) line items are not impacted net working capital definition by anything on the CFS, so we just extend the Year 0 amount of $20m to Year 1. With the assets and liabilities side of the balance sheet complete, all that remains is the shareholders’ equity side.
This amount will appear in step 4 when we reconcile the beginning cash balance to the ending cash balance. In these cases, revenue is recognized when it is earned rather than when it is received. This causes a disconnect between net income and actual cash flow because not all transactions in net income on the income statement involve actual cash items. Therefore, certain items must be reevaluated when calculating cash flow from operations. In the current year, Clear Lake took out additional notes payable (a cash inflow). We can see this by the increase in their notes payable account from the prior year to current year ($40,000 to $50,000).
To opt-in for investor email alerts, please enter your email address in the field and select at least one alert option. After submitting your request, you will receive an activation email to the requested email address. Certain prior period amounts have been reclassified to conform to the 2024 presentation of financial information throughout the press release. PwC refers to the US member firm or one of its subsidiaries or affiliates, and may sometimes refer to the PwC network. This content is for general information purposes only, and should not be used as a substitute for consultation with professional advisors. Decide whether you will use the direct method or the indirect method to prepare the CFS.
It means that core operations are generating business and that there is enough money to buy new inventory. Negative cash flow should not automatically raise a red flag without further analysis. Poor cash flow is sometimes the result of a company’s decision to expand its business at a certain point in time, which would be a good thing for the future. These figures can also be calculated by using the beginning and ending balances of a variety of asset and liability accounts and examining the net decrease or increase in the accounts.